




The Indonesian House of Representatives (DPR RI) and the government have officially passed the 2027 State Budget Law (UU APBN), which, through Article 37, grants the Minister of Finance the authority to conduct examinations and/or special audits concerning the refund of tax overpayments, or restitution. Minister of Finance Suahasil Nazara emphasized that this authority is part of restitution management to ensure taxpayer compliance—including matters related to invoices, transactions, and relationships between taxpayers—while continuing to respect the rights of taxpayers. Meanwhile, tax consultants and observers highlighted the importance of implementing a risk-based approach so that restitution oversight does not add to the taxpayers' burden or potentially hinder cash flows, particularly for businesses that routinely file for restitution, such as export-oriented industries..
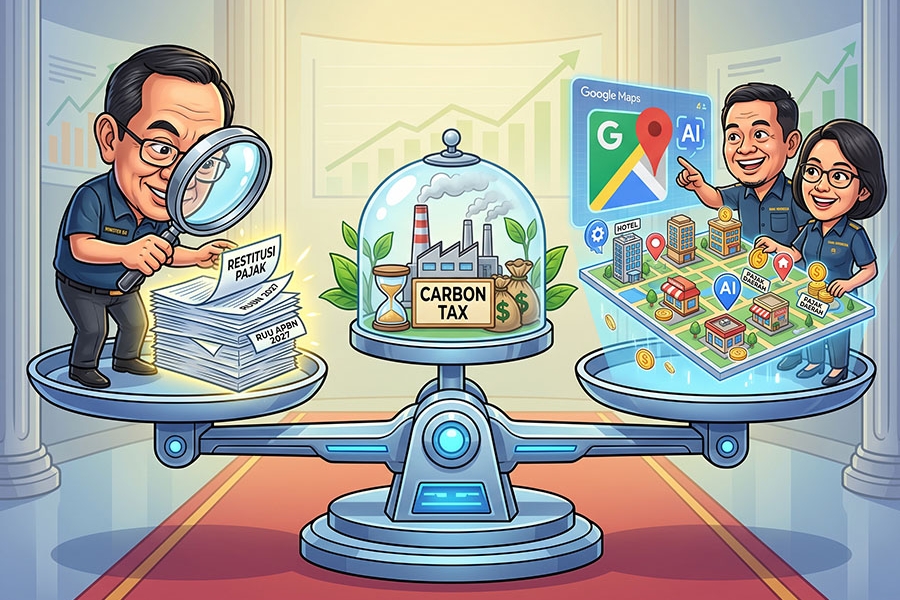
The DPR RI has officially passed the 2027 State Budget Law (UU APBN), which contains provisions regarding examinations and/or special audits for the refund of tax overpayments, or restitution. Based on Article 37 of the 2027 UU APBN, the Minister of Finance has the authority to conduct examinations and/or audits of state revenues, including examinations and/or special audits concerning the refund of tax overpayments.
Further provisions regarding the examination and/or audit of state revenues, including the procedures for refunding tax overpayments during examinations and/or special audits, will be regulated through a Minister of Finance Regulation (PMK). These provisions are more specific than those in the 2026 UU APBN because they explicitly include examinations and/or special audits for tax restitution. Furthermore, the examinations and/or audits referred to in Article 37 can be carried out through a joint audit mechanism.
The Minister of Finance explained that this authority is part of the restitution management carried out by the government through the Ministry of Finance and the Directorate General of Taxes (DJP) to ensure the restitution process complies with regulations. The government continues to respect the rights of taxpayers who apply for restitution while simultaneously ensuring compliance regarding tax invoices, transactions, and relationships among taxpayers during the restitution application process.
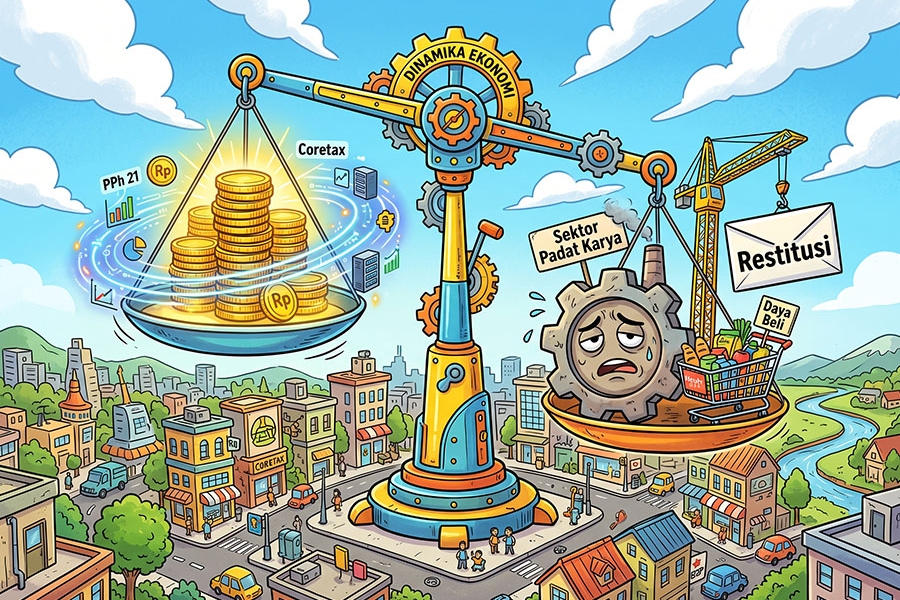
The Minister of Finance also stated that the government takes economic conditions into account in managing tax restitution. Export-oriented industries and labor-intensive industries are considered vital sectors to support because they play a key role in creating jobs and boosting exports.
On the other hand, tax consultants and observers raised a number of questions regarding the design and implementation of these special audits, including potential changes to the long-standing restitution mechanisms.
Tax consultants and policy observers assess that special audits have the potential to alter the currently applied restitution mechanism. They highlighted the risk of an additional burden on taxpayers if special audits end up adding another layer of examination to the restitution process. This condition requires particular attention for taxpayers who routinely apply for Value Added Tax (VAT) restitution, including exporters, because delayed refunds can tie up working capital and incur additional financing costs.
The experts also questioned the relationship between these special audits and the restitution mechanism already regulated in the Law on General Provisions and Tax Procedures (UU KUP). Currently, restitution through examination is regulated under, among others, Article 17B of the UU KUP, while preliminary refunds through research are regulated under Article 17C and Article 17D. According to him, it still needs to be clarified whether these special audits will change the existing mechanisms or establish a completely new one.
To anticipate this potential additional burden, the experts proposed that the implementation of special audits utilize a risk-based approach. He cited the practices of the Australian Taxation Office (ATO), where low-risk taxpayers can obtain restitutions faster through digital processes, while taxpayers showing indications of higher risk may undergo a more in-depth examination. This approach, according to Raden, could be combined with Compliance Risk Management (CRM) so that examinations are not applied uniformly to all taxpayers.
The implementation of special tax restitution audits in the 2027 UU APBN adds to the government's oversight instruments in the process of refunding tax overpayments. For taxpayers, especially businesses that routinely apply for restitution, the fulfillment of invoice administration, transaction recording, and tax documentation in accordance with regulations is becoming increasingly important. At the same time, the execution of this oversight must continue to respect the rights of taxpayers to restitutions that meet the regulatory requirements.
Going forward, the effectiveness of these provisions will depend on the implementing regulations through the PMK, including those regarding the mechanism and procedures for special audits. The risk-based approach proposed by consultants could be taken into consideration so that oversight can proceed without hindering restitutions that meet the requirements. For taxpayers, consistently organizing and fulfilling tax documentation will be a crucial step in facing the implementation of these provisions.










 tpc.consulting
 tpc.consulting
 info@taxindo.co.id