



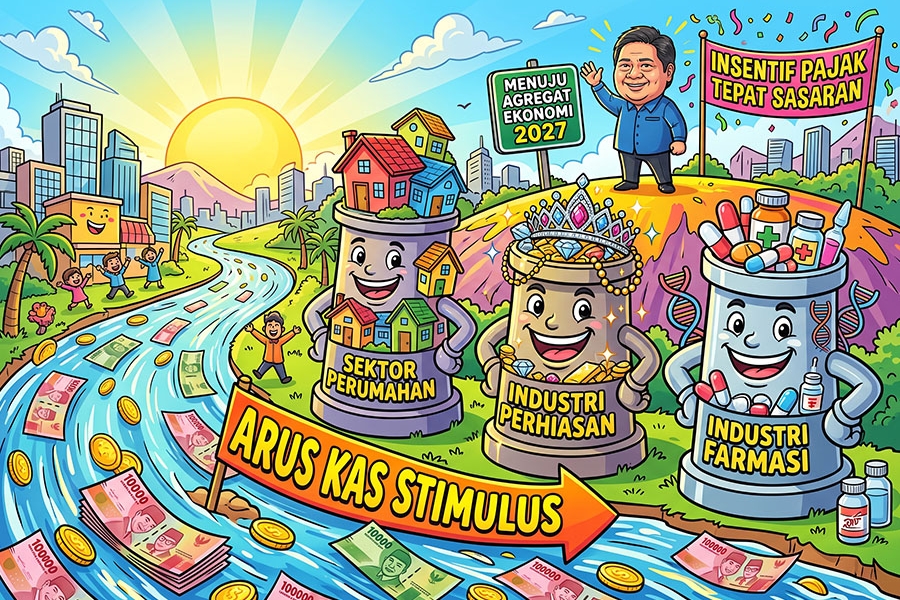
The government is extending the Government-Borne Value Added Tax (VAT DTP) for the housing sector into 2027 and preparing adjustments to the VAT facility standards for the jewelry industry by lowering the precious metal purity threshold from 99.99% to 99.9%. Meanwhile, the pharmaceutical industry highlights the importance of certainty in restitution disbursement timelines amid the implementation of special audits and pushes for risk-based supervision so that the examination process does not prolong the refund of tax overpayments..
The government will continue the Government-Borne Value Added Tax (VAT DTP) facility for the housing sector in 2027. The Coordinating Minister for Economic Affairs stated that the government will maintain the 100% VAT DTP for the purchase of houses with a selling price of up to Rp2 billion. For houses with a selling price of more than Rp2 billion up to Rp5 billion, the 100% VAT DTP is granted on the portion of the selling price up to Rp2 billion, while the price portion above Rp2 billion remains subject to VAT in accordance with applicable regulations.
This policy is a continuation of the housing sector's VAT DTP facility implemented by the government in 2026. Based on Minister of Finance Regulation (PMK) Number 90 of 2025, the facility applies to the handover of new landed houses or flats in ready-to-live-in condition with a maximum selling price of Rp5 billion. The housing units must also meet administrative requirements, including having a house identity code registered in the SIKUMBANG application or BP Tapera.
Through the continuation of this incentive, the government maintains fiscal support for the housing sector by providing a 100% VAT DTP according to the established price limits and requirements. Meanwhile, technical provisions regarding the implementation of the VAT DTP facility for 2027 are still pending regulations that will govern the provision of incentives for that year.
In addition to extending the VAT incentive for the housing sector in 2027, the government is also preparing adjustments to the VAT facility for the jewelry industry. This adjustment relates to the precious metal purity standard that qualifies for the VAT facility.
The Coordinating Minister for Economic Affairs announced that the government will lower the precious metal purity standard from 99.99% to 99.9%. Changes to these provisions will be outlined in a Government Regulation (PP) currently being prepared by the government.
The government will soon finalize the drafting of the PP, and the new provisions will take effect once the regulation is issued. Thus, the change in the precious metal purity standard to 99.9% is not yet in effect and awaits the completion of the regulation as the basis for its implementation.
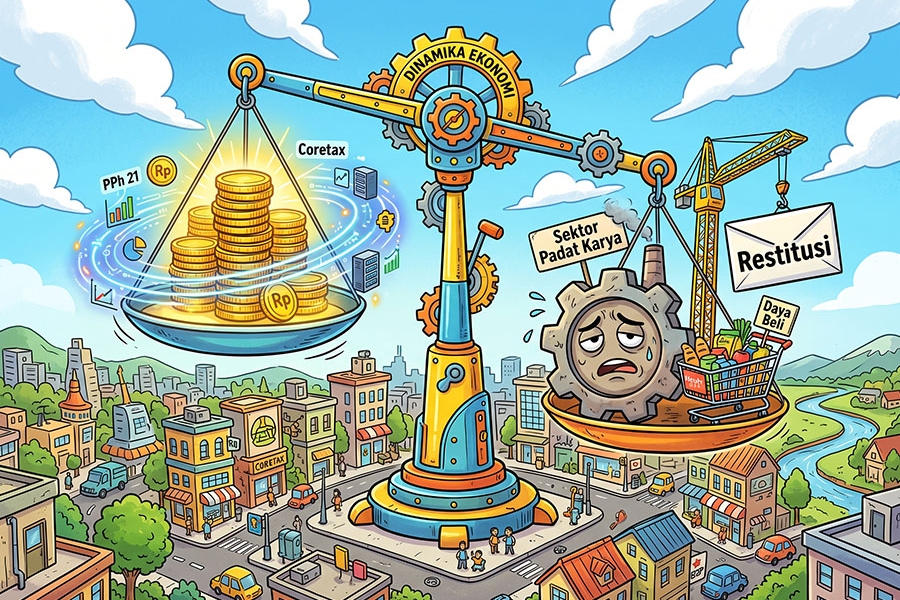
As the government prepares adjustments to the VAT facility for the jewelry industry, business actors' attention is also drawn to the tax restitution supervision policy. The pharmaceutical industry urges the government to ensure that the implementation of special restitution audits does not prolong disbursement times and add uncertainty for companies.
The Chairman of the Biopharmaceutical and Pharmaceutical Raw Materials Association, FX, stated that the pharmaceutical industry does not object to stricter supervision because compliance and audits have become integral to business activities in a highly regulated sector. However, he emphasized the importance of certainty regarding restitution disbursement timelines because delays can pressure company cash flows and working capital needed for purchasing raw materials, production, inventory, labor, and fulfilling various regulatory requirements.
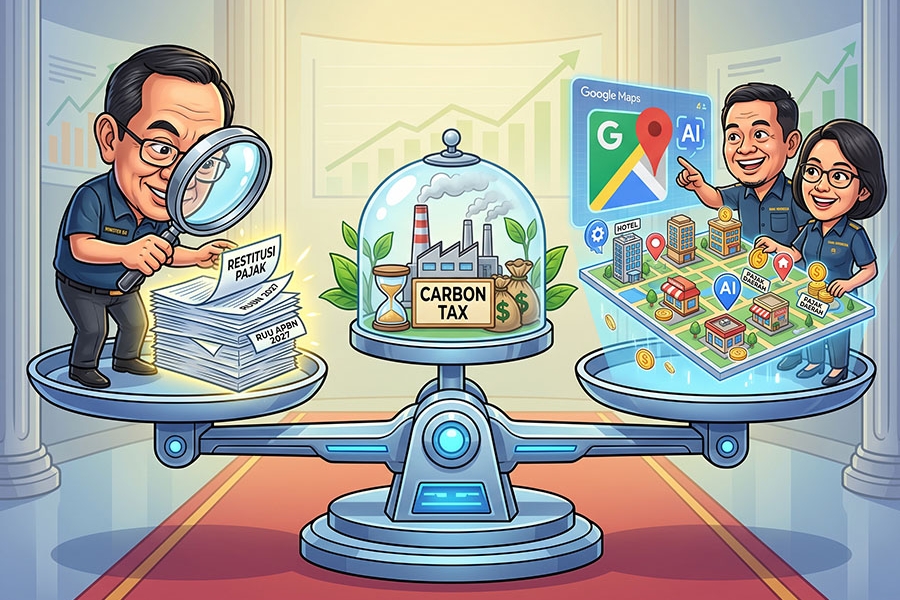
The Chairman also encourages the government to implement risk-based restitution examinations. According to him, taxpayers with a strong compliance record and verifiable transactions could receive a faster restitution process, while more in-depth examinations could be directed at taxpayers or transactions presenting risk indicators. This proposal was made in response to Article 37 of the 2027 State Budget (APBN), which grants the Minister of Finance the authority to conduct examinations and audits of state revenues, including special audits regarding the refund of tax overpayments.
This series of policies demonstrates the government's efforts to align tax policies with the needs of the business sector, ranging from the continuation of the Government-Borne VAT (VAT DTP) incentive for the housing sector to adjusting VAT facility standards for the jewelry industry. At the same time, the pharmaceutical industry highlights the importance of certainty in the restitution process so that the implementation of special audits does not hinder the disbursement of tax overpayments.
The sustainability of incentives, adjustment of regulations, and certainty in administrative processes are the common threads linking these three developments. While the government prepares new provisions for the jewelry industry's VAT facility, players in the pharmaceutical industry are pushing for the implementation of risk-based supervision to ensure examinations proceed without prolonging restitution disbursement times











 tpc.consulting
 tpc.consulting
 info@taxindo.co.id