




The government is strengthening the collection of cross-jurisdictional tax arrears as one of the strategic activities of the Directorate General of Taxes (DJP) in 2027 by utilizing the Assistance in the Collection of Tax Claims (AIC) cooperation with 81 countries or jurisdictions. On the other hand, customs and excise revenues reached Rp240.28 trillion by September 2026, while the implementation of the Global Minimum Tax alters the calculation of tax holiday benefits for affected companies. These developments indicate that state revenue policies must proceed in tandem with strengthened oversight and adjustments to global tax developments..
The Indonesian government will strengthen the collection of cross-jurisdictional tax arrears as one of the strategic activities of the Directorate General of Taxes (DJP) in 2027. Currently, Indonesia has established an Assistance in the Collection of Tax Claims (AIC) framework with 81 countries or jurisdictions, comprising 72 countries under the Convention on Mutual Administrative Assistance in Tax Matters (MAAC) and nine countries or jurisdictions under Double Taxation Agreements (DTA / P3B).
Through this cooperation, the DJP can request assistance from partner countries' tax authorities to execute various collection efforts against tax defaulters who reside or possess assets in the relevant jurisdictions. Such assistance may include freezing financial accounts as well as the seizure and sale of assets belonging to the tax guarantor abroad. Its implementation remains subject to the domestic legal provisions of the requested country or jurisdiction.
The collection of cross-jurisdictional tax arrears is one of the eight strategic activities of the DJP in 2027. For that year, the DJP has been assigned a revenue target of Rp2,593.35 trillion. The substantial amount of tax receivables is also a key context for strengthening collection efforts. Based on the 2025 audited Central Government Financial Report (LKPP), gross tax receivables were recorded at Rp116.7 trillion, consisting of receivables at the DJP amounting to Rp83.6 trillion and the Directorate General of Customs and Excise (DJBC) at Rp33.1 trillion. Observers assess that this cooperation has the potential to strengthen long-term law enforcement and create a deterrent effect, even though cash receipts from cross-jurisdictional collections cannot be obtained instantly.
The strengthening of state revenue is also evident from the customs and excise performance, which recorded solid growth up to September 2026.
State revenue from customs and excise up to September 2026 reached Rp240.28 trillion, an increase of 8.57% compared to the same period the previous year. This realization has reached 71.51% of the 2026 revenue target of Rp336 trillion. Finance Minister Suahasil Nazara emphasized that these revenues serve as state resources to finance development, strengthen public services, safeguard public purchasing power, and support various priority government programs.
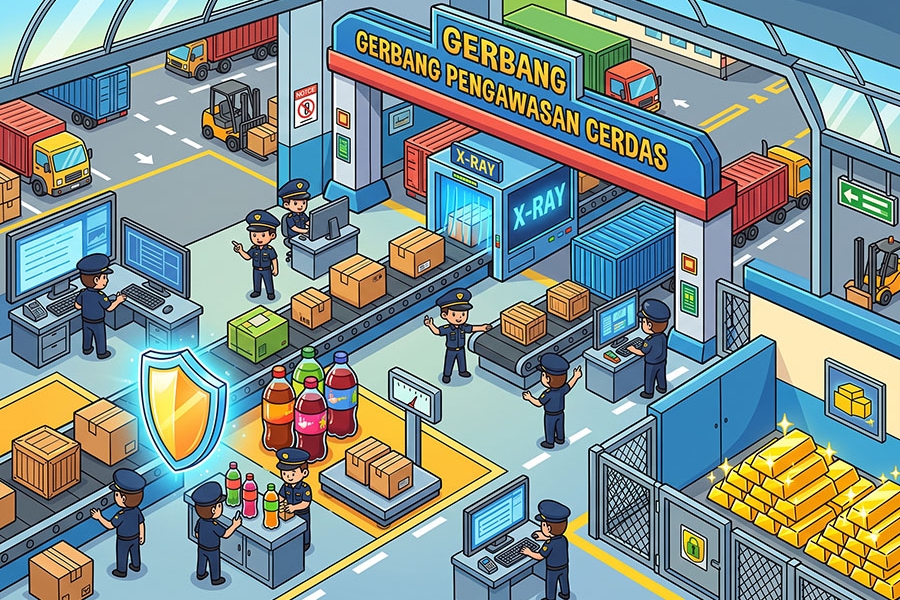
On the supervision front, Suahasil requested Customs to strengthen enforcement against smuggling and the circulation of illegal goods. This supervision covers goods that endanger the public, strategic commodities, and natural resources such as gold and nickel, as well as illegal imported goods like ballpres (bales of used clothing) and illegal rice that negatively impact the public and the national economy. At the same time, Customs is urged to provide facilitation, speed, transparency, and certainty for the public and the business sector to smoothen the flow of goods, enhance business competitiveness, boost exports, and support national economic growth.
This balance among the functions of revenue generation, supervision, and service becomes increasingly relevant as global tax changes also affect the calculation of incentive benefits for investors.
The implementation of the Global Minimum Tax (GMT) through the OECD/G20 Inclusive Framework Pillar 2 alters the calculation of tax holiday facility benefits for affected companies. With the global minimum tax provisions in place, the benefits of tax reductions through tax holidays must be re-evaluated in relation to the applicable minimum tax rate. This condition compels multinational companies to calculate the impact of tax incentives on their overall tax burden within the new global tax environment.
These changes also drive the need to review the design of investment incentives to ensure that the provided policies remain relevant in the face of the global minimum tax implementation. Thus, the evaluation of tax holiday benefits becomes an integral part of adjusting investment policies amidst changing international tax regulations.
This series of developments carries significant implications for business actors and investors. Companies with cross-jurisdictional obligations or assets must pay close attention to the development of international tax collection mechanisms. Business actors engaged in international trade must also observe customs compliance while ensuring the flow of goods adheres to regulations. Meanwhile, companies utilizing tax holiday facilities need to consider the changing global tax environment when evaluating the incentive benefits they receive.
Ultimately, the strengthening of state revenue is proceeding through various instruments, ranging from the collection of cross-jurisdictional tax arrears to the optimization of customs revenue and supervision, as well as the adjustment of investment incentive policies. The government must maintain a careful balance between revenue, supervision, service, and investment competitiveness, while business actors must continuously adapt their compliance strategies and tax planning to evolving national and global policy developments.













 tpc.consulting
 tpc.consulting
 info@taxindo.co.id