



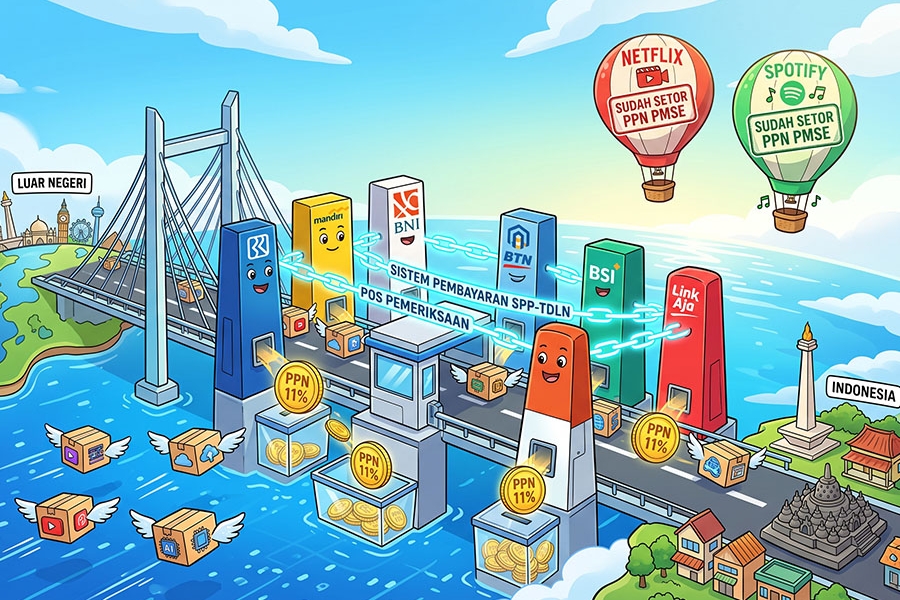
The government began implementing SPP-TDLN on September 25, 2026, to strengthen the collection of Value Added Tax (VAT) on foreign digital transactions. This mechanism involves five banks and one fintech company as issuers in the collection of VAT for eligible transactions. Meanwhile, platforms such as Netflix and Spotify will continue to use the PMSE VAT mechanism, as they have already been collecting VAT through that system..
The Directorate General of Taxes (DJP) began implementing the Tax Collection System for Foreign Digital Transactions (SPP-TDLN) on September 25, 2026. This system serves as a VAT collection mechanism for the utilization of foreign digital goods and services in Indonesia. The government emphasized that SPP-TDLN is not a new tax and does not alter the VAT rate. Instead, it is a technology-based mechanism designed to strengthen the administration of VAT collection on foreign digital transactions that meet tax provisions. The implementation of this system is also a response to the shift in economic activities toward digital business models, which include the use of applications, software, cloud services, streaming, AI subscriptions, games, and various digital services and data from abroad.
After completing the sandboxing phase and stabilization period, SPP-TDLN began operating on September 25, 2026. In its initial phase, the system involves PT Jalin Pembayaran Nusantara as the system operator, along with five banks and one fintech company as designated issuers. The five banks are BRI, Bank Mandiri, BNI, BTN, and Bank Syariah Indonesia, while LinkAja serves as the issuer from the fintech sector. These issuers are responsible for collecting VAT on eligible foreign digital transactions, as well as remitting and reporting the collected VAT.
Under this mechanism, foreign merchants and service providers included in the SPP-TDLN scheme must account for VAT in transactions with customers in Indonesia. This VAT can be collected through payment system intermediaries or other designated entities before the remaining funds are forwarded to the foreign merchant or service provider. The involvement of these banks and the fintech company is part of the DJP's effort to strengthen VAT collection on cross-border digital transactions, including those from foreign platforms that have not yet collected VAT through the PMSE (Electronic System Trading) VAT mechanism.
Consequently, the implementation of SPP-TDLN has implications for foreign platforms integrated into the mechanism. These platforms are required to account for VAT in their transactions with Indonesian customers, while the collection can be carried out through established payment mechanisms. This scheme broadens the channels for VAT collection on foreign digital transactions by involving parties within the payment system.
However, the implementation of SPP-TDLN does not apply to all foreign digital platforms. Netflix and Spotify, for example, are not included in this new mechanism because they have already been collecting VAT through the PMSE VAT mechanism. Thus, the existence of SPP-TDLN does not replace the PMSE VAT mechanism; rather, it complements the collection of VAT on foreign digital transactions that are not yet covered by it.
For foreign digital business actors, the rollout of SPP-TDLN means that the VAT collection aspect must be carefully considered in transactions with Indonesian customers. Business actors need to understand the collection mechanism applicable to their transactions, specifically distinguishing between transactions that fall under the PMSE VAT mechanism and those covered by SPP-TDLN. For the public, this implementation does not create a new type of tax but instead reinforces the VAT collection mechanism for foreign digital transactions that are already subject to VAT.
The implementation of SPP-TDLN demonstrates that the government is taking steps to strengthen VAT collection administration in line with the growth of cross-border digital transactions. Digital business actors must ensure that their transactions and VAT collection mechanisms comply with applicable regulations. Concurrently, the government must maintain system integration to ensure that the expansion of tax collection runs effectively and does not result in double taxation of VAT.









 tpc.consulting
 tpc.consulting
 info@taxindo.co.id