



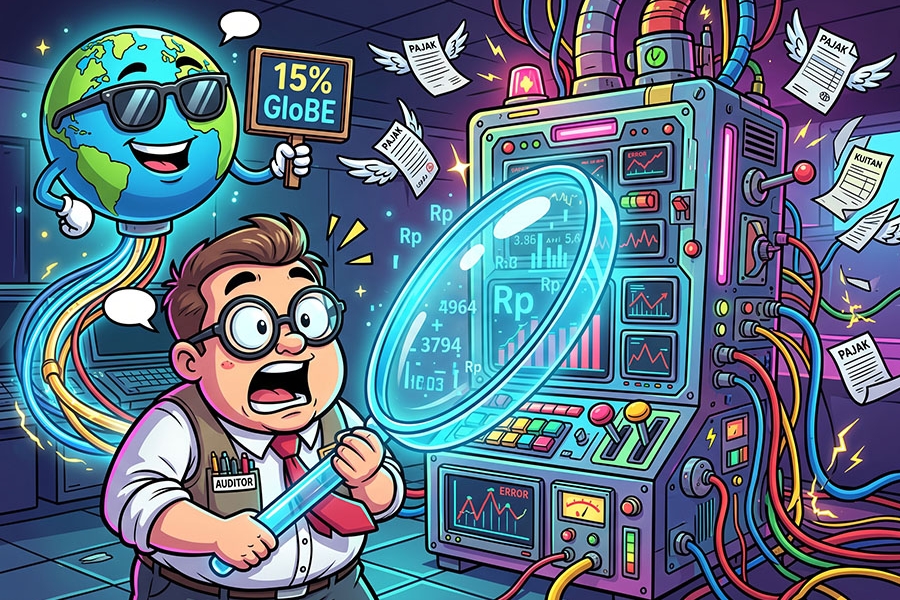
The Supreme Audit Agency (BPK) discovered weaknesses in the Directorate General of Taxes' information system that potentially hinder the optimization of tax revenues. BPK also highlighted the granting of tax facilities to two business entities deemed unqualified for the incentives. Meanwhile, the Directorate General of Taxes noted that approximately 5,600 taxpayers have been registered within the implementation scope of the Global Minimum Tax (GloBE)..
The strengthening of tax administration has become a focal point in managing Indonesia's state revenue. In the Summary of Semester Examination Results (IHPS) I/2026, the Supreme Audit Agency (BPK) revealed several issues related to the capabilities of the tax information system and the accuracy of granting facilities to business actors. Concurrently, the implementation of the global minimum tax introduces new obligations for multinational corporate groups that meet specific criteria.
BPK found that the Directorate General of Taxes Information System (SIDJP) is inadequate in detecting late and underpaid taxes, as well as payments that do not correspond to the correct tax period. This condition potentially leaves administrative sanctions—which should be followed up through the issuance of Tax Collection Letters (STP)—uncollected. Furthermore, the system is not yet fully capable of verifying the consistency of tax invoices with transactions, payments, and VAT reporting in the Periodic VAT Returns (SPT Masa PPN). BPK also identified indications of tax invoices that had not been reported by taxpayers. Based on these findings, BPK recommended the Minister of Finance to evaluate the implementation of SIDJP and follow up on the evaluation results according to previous audit recommendations.
These oversight issues are closely related to another aspect of tax administration: the precision of granting tax facilities to businesses.
In IHPS I/2026, BPK discovered that two business entities received tax holiday and/or tax allowance facilities despite having commenced commercial production before applying for the incentives. BPK attributed this finding to inadequate verification by the Ministry of Investment and Downstreaming/BKPM regarding the Estimated Start of Commercial Production (SMB) data. The Online Single Submission (OSS) system was also deemed insufficient in detecting the risk of facility applications by businesses already engaged in commercial production. BPK recommended the development of chronological recording features, data exchange with the DJP, coordination to follow up on the facilities granted to the two businesses, and the formulation of rigorous verification procedures for SMB dates.
In addition to improving the oversight and verification of facilities, the government is navigating international tax policy developments that affect multinational corporate groups.
The Directorate General of Taxes (DJP) recorded that around 5,600 taxpayers have been registered within the scope of the Global Anti-Base Erosion (GloBE) minimum tax implementation as of mid-October 2026. Indonesia has implemented these provisions since 2025 based on Minister of Finance Regulation Number 136 of 2024, with administrative procedures regulated in the Director General of Taxes Regulation Number PER-6/PJ/2026. This regime applies to multinational corporate groups that meet the consolidated turnover threshold of at least EUR 750 million. GloBE aims to ensure that the effective tax rate on covered profits reaches at least 15% in every relevant jurisdiction. Thus, the figure of 5,600 represents the number of taxpayers falling within the implementation scope, rather than the number definitively owing additional top-up taxes.
In its execution, Indonesia utilizes mechanisms such as the Domestic Minimum Top-up Tax (DMTT)—also known in the Indonesian context as QDMTT—and the Income Inclusion Rule (IIR). Both mechanisms allow for the imposition of additional taxes according to provisions if the effective tax rate falls below the applicable minimum threshold. In May 2026, the DJP recorded potential revenues from the QDMTT and IIR schemes at around Rp4.49 trillion, while the application of the Undertaxed Profits Rule (UTPR) was still under further review. Optimizing revenue from GloBE continues to face challenges, including the need for socialization, uniform understanding among tax officers, tax information validity, and certainty regarding alternative incentives for companies covered by the regime.
For business actors, these developments underscore the vital importance of accurate and well-documented tax management. Companies must ensure the accuracy of their tax payments and reporting, verify their eligibility for utilizing tax facilities, and evaluate whether their corporate groups meet GloBE criteria. For multinational companies covered by the regime, tax planning must also account for the calculation of effective tax rates, reporting obligations, and potential additional taxes. Meanwhile, investors need to assess tax incentives alongside other factors—such as regulatory certainty, operational costs, and market conditions—when making investment decisions.
Moving forward, the strengthening of administrative systems, facility verification, and the execution of the global minimum tax must proceed in a coordinated manner. The government needs to improve data quality and oversight consistency while providing definitive certainty regarding tax provisions and investment incentives. On the flip side, business actors must strengthen compliance and conduct regular evaluations of their tax positions. The optimization of state revenue will be far more sustainable when supported by effective supervision, precisely targeted incentives, and robust policy certainty for the business world.














 tpc.consulting
 tpc.consulting
 info@taxindo.co.id