




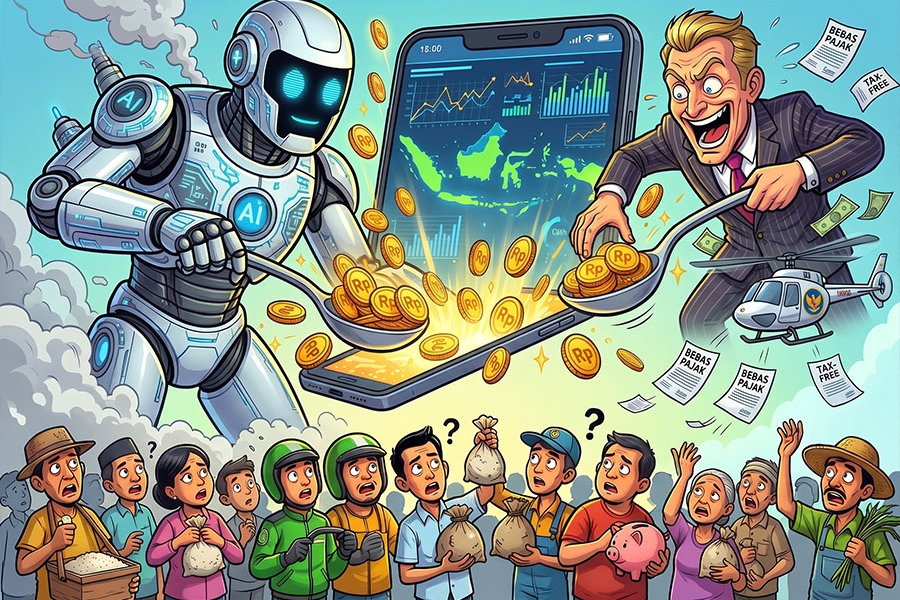
The Directorate General of Taxes disbursed Rp208.68 trillion in tax refund claims through October 2026, prioritizing MSMEs and labor-intensive manufacturing facilities. Concurrently, business leaders cautioned that delayed refund processing threatens to paralyze companies operating on slim profit margins. Economic analysts urged authorities to guarantee equitable refund timelines for exporters and general manufacturers to safeguard national working capital reserves..
.
The Directorate General of Taxes disbursed Rp208.68 trillion in tax refund claims through October 2026, prioritizing MSMEs and labor-intensive manufacturing facilities. Concurrently, business leaders cautioned that delayed refund processing threatens to paralyze companies operating on slim profit margins. Economic analysts urged authorities to guarantee equitable refund timelines for exporters and general manufacturers to safeguard national working capital reserves.
The Directorate General of Taxes under the Ministry of Finance realized tax refund disbursements totaling Rp208.68 trillion as of October 31, 2026. Director General of Taxes emphasized that the government deliberately accelerated refund distributions to provide fresh operational liquidity, ensure steady manufacturing schedules, and sustain national workforce absorption. Authorities focused this payment acceleration directly toward micro, small, and medium enterprises (MSMEs) alongside labor-intensive industrial factories.
The government distributed Rp7.14 trillion in tax refunds to 125,375 MSME applicants throughout the first ten months of 2026. Average monthly MSME refund disbursements during September and October surged by 86.5% to Rp604.91 billion compared to the monthly average recorded between May and August of Rp324.33 billion. Concurrently, authorities disbursed Rp4.9 trillion to 2,767 labor-intensive corporate applicants, settling 92.1% of received sector filings and leaving Rp418 billion in remaining applications scheduled for completion in November and December.
Tax authorities continue conducting rigorous risk-management audits despite accelerating cash disbursements to the commercial community. This prudent enforcement framework seeks to maintain state financial accounting integrity while preventing fraudulent refund claims. This selective state refund acceleration prompted immediate responses from the business community, which warned that smooth refund distributions represent a matter of survival for corporate operations.
Indonesia Business Council (IBC) Supervisory Board Chairman cautioned the government against allowing tax refund disbursements to stall in the field. Heemphasized that operating cash flow represents the vital lifeline determining enterprise sustainability. Disruptions in refund distributions risk paralyzing ongoing business operations and driving vulnerable corporate enterprises into permanent closure.
Commercial enterprises operating on slim profit margins of 1% to 3% alongside small MSME units face severe risks when authorities withhold refund disbursements. Delaying legitimate corporate tax returns directly drains daily operating cash balances. He urged the government to ensure that tax administrative procedures do not impair enterprise operational liquidity amid challenging economic environments.
Official records indicate that national tax refund realizations previously reached Rp198.71 trillion by the end of September 2026. These returns encompassed Income Tax, Value Added Tax, and Sales Tax on Luxury Goods aimed at preserving industrial vitality. These urgent industrial warnings received strong reinforcement from economic analysts examining sectoral fairness in state refund processing.
Center of Reform on Economics (CORE) Economist stressed that tax refunds constitute a legal entitlement belonging to taxpayers rather than government benevolence or fiscal subsidies. Withholding legitimate refunds effectively allows the state to utilize corporate funds without providing interest compensation. Tax authorities must avoid prioritizing labor-intensive industries exclusively, establishing instead predictable refund processing timelines for general manufacturing and export enterprises carrying excess VAT input claims amid currency depreciation and rising import costs.
IEF Research Institute Executive Director pointed out that the Rp4.9 trillion disbursed to labor-intensive industries accounts for merely 2.3% of total national tax refunds. The vast majority of delayed capital remains concentrated among commodity exporters, export-oriented manufacturing firms, mining operators, and wholesale trading corporations. He criticized regulatory restrictions under Minister of Finance Regulation Number 28 of 2026, which lowered the expedited VAT refund threshold from Rp5 billion to Rp1 billion, arguing that this threshold is too low for mid-sized export corporations.
He highlighted statutory obligations under Article 17B of the General Tax Provisions Law (UU KUP), which requires the state to pay interest compensation if audit determinations exceed twelve months. To avert escalating net budget liabilities in 2027, he recommended that DJP publish pending refund queue data periodically. Greater queue transparency would enhance commercial certainty while presenting an accurate picture of net state tax collections to the public.
Selective refund acceleration policies and tightened audit controls deliver direct implications for enterprise working capital and national investment confidence. For industrial exporters and manufacturing managers, withheld input VAT refunds deplete operating cash balances and inflate commercial debt financing costs amid elevated interest rates and currency pressures. Meanwhile, for MSME operators and industrial factory workers, reliable tax refund distributions preserve business liquidity and shield personnel from displacement risks.
In conclusion, fiscal authorities must harmonize regulatory compliance enforcement with corporate liquidity preservation by ensuring equitable tax refund timelines across all economic sectors. The government is recommended to review expedited refund thresholds within PMK 28/2026, deploy automated risk-based audit pathways across Coretax, and disclose pending refund queues through digital portals. Business operators are advised to organize input tax invoices transparently and optimize digital accounting records to accelerate data verification during tax audits.













 tpc.consulting
 tpc.consulting
 info@taxindo.co.id