



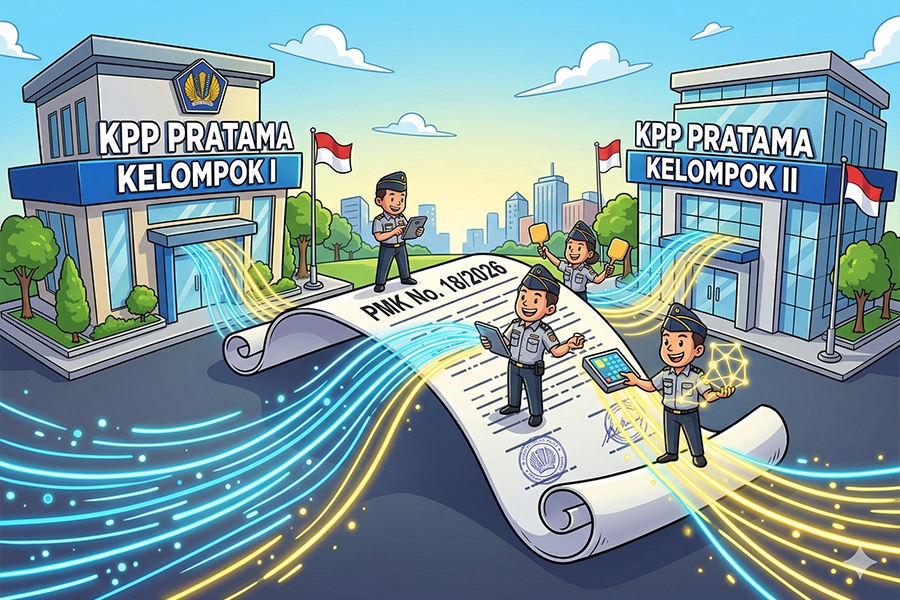
The Ministry of Finance has officially implemented an architectural overhaul of the Directorate General of Taxes via PMK Number 18 of 2026 to accelerate national tax oversight efficiency. This restructuring divides the Primary Tax Service Offices into two supervisory clusters, consolidates various law enforcement sections, and establishes specialized units for listed corporations and extractive sectors. This strategic maneuver is widely expected to streamline bureaucratic pipelines while comprehensively curbing state revenue leakages.
The operational landscape of the national tax authority is undergoing a fundamental shift following the enactment of Minister of Finance Regulation Number 18 of 2026 in early April. This novel directive repeals the previous legal framework and diversifies the Tax Service Office hierarchy into four distinct echelons. The most strategic innovation materializes in the inception of specialized units exclusively dedicated to overseeing the financial compliance of foreign direct investments, foreign entities, the oil and gas industry, and publicly listed corporations. Sharpening this supervisory focus becomes essential to mitigate liability avoidance risks within heavily capitalized sectors.
This architectural realignment further permeates the foundational operational tier by dichotomizing the Primary Tax Service Offices (KPP Pratama) into two specific clusters. In stark contrast to the preceding regulation which homogenized structures across all regions, the new formation divides these units into Group I and Group II. This structural capacity divergence is heavily pronounced within the supervisory domain, where Group I units are fortified with six supervisory sections, whereas Group II operates optimally with five supervisory sections. This capacity differentiation allows authorities to proportionately respond to workloads in accordance with regional operational complexities.
Bureaucratic pipeline efficiency is manifested through a radical overhaul of internal section structures. The Data and Information Processing function has now transformed into a Data Quality Assurance section to guarantee analytical precision, while examination and collection sections have been functionally amalgamated with the valuation section to centralize law enforcement capabilities. Concurrently, authorities liquidated independent extensification and education sections. Extensification mandates are directly integrated into the supervision section, education and consultation functions are centralized within the service section, and the Supervision and Consultation nomenclature has been vastly simplified into pure supervision sections.
The pruning of internal bureaucracy and the classification of service units based on supervisory volume represent the government's decisive maneuver toward a risk-based compliance taxation regime. The amalgamation of examination and collection functions under a single operational command mathematically compresses audit processing times, subsequently driving down the national collection costs. For the corporate landscape, this novel architecture indicates that fiscal authorities now possess vastly more integrated cross-section analytical capacities to autonomously detect anomalies across business entity tax reporting cycles.
This structural modernization of taxation underscores the state's severe commitment to cultivating an agile, data-driven oversight ecosystem. Multinational corporations and local business entities are highly recommended to immediately streamline the accuracy of their internal accounting data to mitigate potential legal disputes under this increasingly structured tax supervision regime.
The copy of Ministry Finance Regulation Number 18 Year 2016 can be accessed here.











 tpc.consulting
 tpc.consulting
 info@taxindo.co.id