



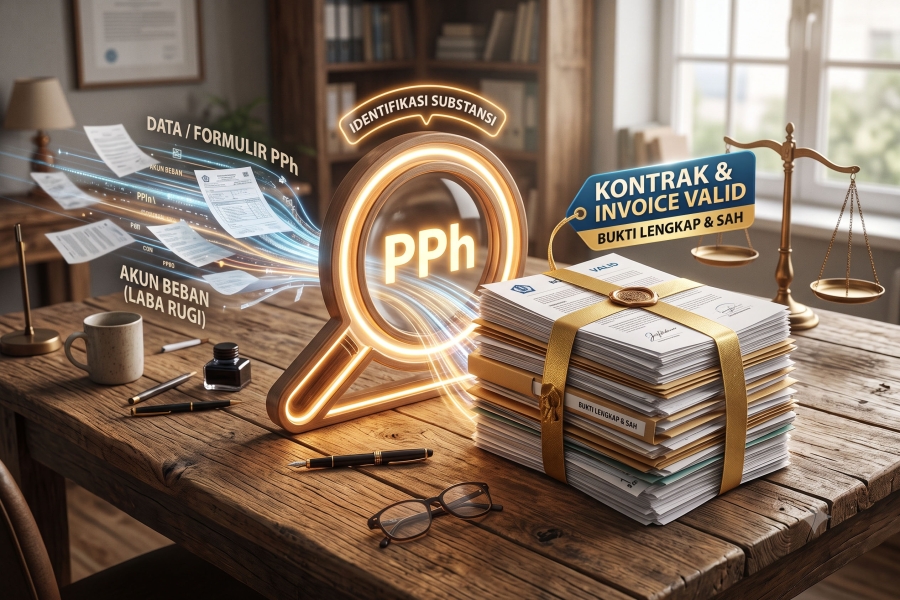
The income statement is a financial statement that not only reflects a company's performance but also serves as a crucial source of information for identifying the fulfillment of tax obligations. Various expense accounts listed therein—such as employee salaries and allowances, professional service fees, commissions, legal fees, payments to contract workers, and other operational costs—fundamentally possess different tax characteristics. Therefore, it is not enough for a company to merely ensure that transactions have been recorded in accordance with accounting standards; it also needs to understand whether these payments constitute an Income Tax (PPh) object, the applicable type of Income Tax, and the party responsible for withholding the tax. Inaccuracies in identifying the Income Tax object can lead to tax withholding errors, which ultimately have the potential to cause corrections during the tax audit process.
In practice, determining the Income Tax object does not rely on the account name listed in the income statement, but rather on the actual substance of the transaction. This means that companies must identify the party receiving the income, the legal relationship underlying the transaction, and the form of compensation provided before determining the type of Income Tax to be withheld. For instance, the legal fees account does not always incur the same tax treatment. Payments made to individual advocates or experts inherently have different characteristics compared to payments made to corporate law firms. The same principle applies to accounts such as contract staff, commission, transport allowance, meal allowance, and various other expense accounts, which in practice often require further analysis of their economic substance.[1] Consequently, a single account name does not necessarily reflect a single, uniform tax treatment.
To ensure that the tax treatment for these transactions has been applied correctly, Tax Auditors may employ various audit methods and techniques in accordance with prevailing regulations. One technique that can be used is equalization or reconciliation, which is the process of matching two or more related data sets or items to identify discrepancies that require further explanation. This provision is stipulated in Appendix II, numbers 7 and 8 of the Director General of Taxes Circular Letter Number SE-65/PJ/2013.[2] As an illustration, the auditor may match the expense accounts in the income statement with the Income Tax objects that have been withheld and reported in the Tax Return (SPT). If a discrepancy is found, this result does not automatically indicate a tax withholding deficiency; rather, it serves as a basis for conducting further testing on the nature of the transaction and the supporting documents held by the Taxpayer.
This understanding is crucial because, in practice, there is still an assumption that any discrepancy resulting from an equalization automatically constitutes a tax object that has not been withheld or reported. In fact, the primary function of equalization is merely an initial identification technique within the audit process. This aligns with Article 4 letter c of the Director General of Taxes Regulation Number PER-23/PJ/2013,[3] which mandates that an audit must be conducted based on data, information, statements, evidence, and facts obtained and tested objectively and professionally. Furthermore, Article 8 of the Minister of Finance Regulation Number 17/PMK.03/2013[4] emphasizes that the implementation of an audit must be based on competent and sufficient evidence to serve as the foundation for formulating audit findings and conclusions. This principle is also consistent with Article 12 paragraph (3) of the Law on General Provisions and Tax Procedures (UU KUP), which requires the Director General of Taxes to obtain evidence that the tax amount declared by the Taxpayer is incorrect before determining the amount of tax payable. Thus, an equalization discrepancy is essentially just an indication that still requires further evidentiary proof through contracts, invoices, proofs of payment, third-party confirmations, or other relevant documents.
Ultimately, the process of determining the Income Tax object on expense accounts is a combination of understanding the substance of the transaction, prevailing tax regulations, and the company's ability to provide adequate evidence for the applied tax treatment. Documentation such as contracts, invoices, proofs of payment, and other supporting documents are inseparable parts of proving that a transaction has been subjected to the correct type of Income Tax. In this way, not only can the company accurately fulfill its tax obligations, but it also establishes a strong foundation in the event of an audit or when differences in interpretation arise regarding the tax treatment of an expense account. This approach ultimately provides better legal certainty while minimizing the potential for tax corrections and disputes.









 tpc.consulting
 tpc.consulting
 info@taxindo.co.id