



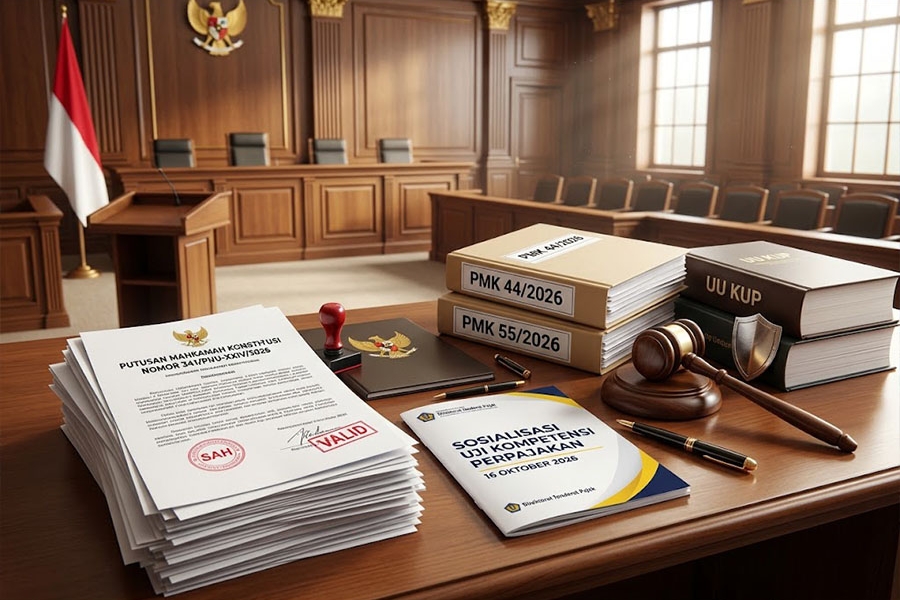
The Constitutional Court has dismissed the judicial review lawsuit in its entirety regarding the delegation of tax competency test regulations. Decision Number 341/PUU-XXIV/2026 reaffirms the legal validity of the Minister of Finance's authority to draft implementing regulations. The Minister of Finance regulates the technical procedures for verifying the competency of tax attorneys through PMK 44/2026 and PMK 55/2026. The Court determined that these regulations do not exceed authority nor restrict citizens' rights. This decision reinforces legal certainty for the national implementation of tax competency tests..
Constitutional Court Decision Number 341/PUU-XXIV/2026, read on October 15, 2026, provides legal certainty regarding the regulations on tax competency tests. During the dissemination session (sosialisasi) of PMK 44/2026, PMK 55/2026, and the tax competency test on October 16, 2026, a speaker from the Directorate General of Taxes, Ms. Meidiati (Bu Meidi), addressed questions from participants and explained the main points of the decision along with its implications for the implementation of the tax competency test.
The Constitutional Court dismissed the Applicant's petition in its entirety. Consequently, the delegation of authority to the Minister of Finance to draft implementing regulations under Article 44E of the KUP Law (General Tax Provisions and Procedures Law), as amended by the HPP Law (Harmonization of Tax Regulations Law), remains valid and requires no amendments.
In its legal considerations, the Court applied the principles established in Constitutional Court Decision Number 63/PUU-XV/2017 mutatis mutandis. This approach indicates that the substance of the case remains fully aligned with the previous ruling, making it unnecessary for the Court to construct a new theoretical foundation or legal doctrine.
The competency requirements for tax attorneys (kuasa perpajakan) originate directly from Article 32 paragraph (3a) of the KUP Law, rather than being created by Minister of Finance Regulations (PMK). Through PMK 44/2026 and PMK 55/2026, the Minister of Finance merely regulates the technical and administrative procedures to verify such competency.
The Court ruled that the Minister of Finance did not exceed her authority and did not restrict the substantive rights of citizens. Therefore, the regulations set forth in PMK 44/2026 and PMK 55/2026 are deemed valid and remain strictly within legal parameters. This ruling simultaneously reinforces legal certainty in the execution of tax competency tests.
Read Constitutional Court Decision 341/PUU-XXIV/2026 here










 tpc.consulting
 tpc.consulting
 info@taxindo.co.id