



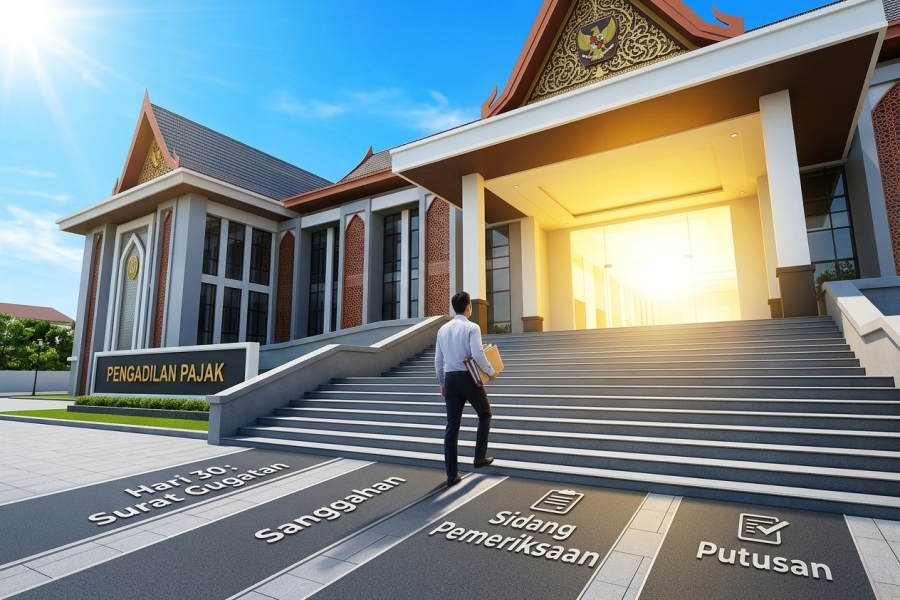
The dispute settlement process for a Lawsuit (Gugatan) at the Tax Court is rigidly regulated under Law Number 14 of 2002 concerning the Tax Court (Tax Court Law). Unlike Appeal (Banding) disputes which concern substantive matters (such as the tax amount), lawsuit disputes are filed against formal procedural aspects, such as the execution of tax collection or decisions issued contrary to procedures. Both the Taxpayer (Plaintiff) and the Defendant (Directorate General of Taxes/DGT or Directorate General of Customs and Excise/DGCE) must understand the hearing stages and prepare specific documents to fulfill the formal requirements so that the filed lawsuit can be processed by the Tax Court.
The examination process of a lawsuit dispute at the Tax Court consists of the following stages:
Aside from the hearing stages, the disputing parties also need to prepare the following documents to ensure the filed lawsuit fulfills both formal and material requirements, namely:












 tpc.consulting
 tpc.consulting
 info@taxindo.co.id